Press Release
Our Response to the SEC’s Proposed Regulation Crypto Assets
Many of our clients operate across several jurisdictions, with the US already a home market or a key area of growth for most of them. Our response to the SEC’s proposed Regulation Crypto Assets draws on our work under MiCA in the EU and in the FCA’s Regulatory Sandbox in the UK. If there’s one theme across every consultation response we’ve written in the last few weeks, it’s how to encourage better, more pragmatic disclosure for assets that can trade in many markets at once.
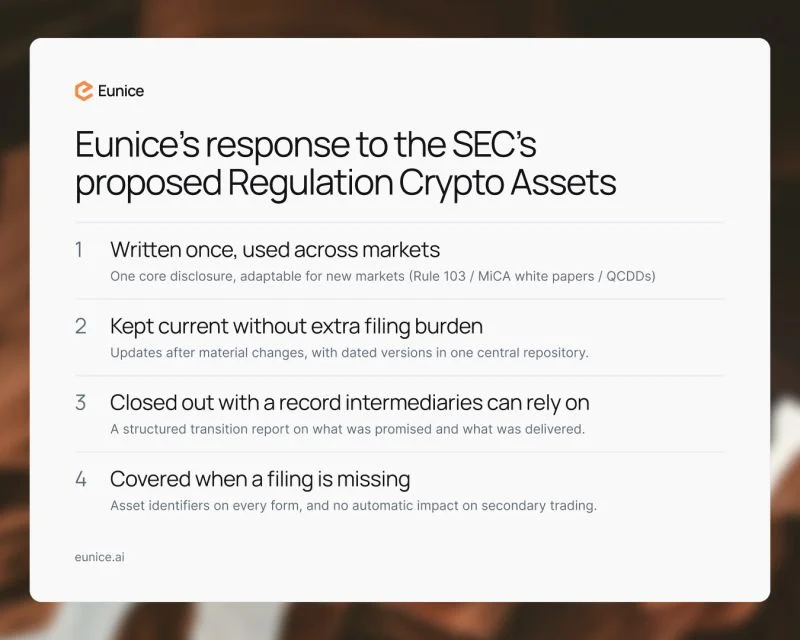
With that in mind, we focused on four practical priorities:
-
Written once, used across markets. Snappy heading aside, Rule 103, the MiCA white paper and the UK’s QCDD ask many of the same core questions. We support a principles-based approach, with a short key-information summary up front and a consistent ordering, which would help issuers prepare one core disclosure and adapt it for each market where it’s offered.
-
Kept current without a disproportionate filing burden. Updates after material changes, with a dated record of each version published through a simple central repository. More generally, simpler, lower-risk filing should encourage more issuers to file.
-
A clear record when an issuer’s promises are fulfilled. Under the proposal, a transition report records when an issuer’s promises to investors have been fulfilled (or abandoned). That report should set out clearly what was promised and what was delivered, so platforms can reasonably rely on it, with scope for someone other than the issuer to file where appropriate.
-
And what happens when an issuer doesn’t file? Projects wind down and teams move on (or become uncontactable), but platforms still need to make a call. In our view, the consequences of a missed filing for secondary trading should be proportionate and predictable. An abrupt restriction would be disruptive for holders and platforms alike. On an operational level, an asset identifier on every filing, with the central repository searchable by asset, would make it easier for platforms to find what’s been formally filed about a token and reach a reasonable view.
This response was led by the brilliant Ana Beslija, who has a real understanding of what filing a disclosure involves in practice.
Originally posted on LinkedIn by Chrislyn Pereira.